Moneyplant
Third place, PIMCO Challenge, TAMUhack X
A robo-advisor that turns a risk questionnaire into a sector portfolio, using LSTM forecasts as the views in a Black-Litterman model.
- Role
- Team, TAMUhack X (2024). My part: the React app, the Django REST backend and login, and the risk questionnaire.
- Stack
Problem
PIMCO’s challenge asked for a robo-advisor. Big firms automate allocation for their clients; we wanted a version anyone could use, which starts from how much risk you can stomach rather than from a ticker list.
What I built
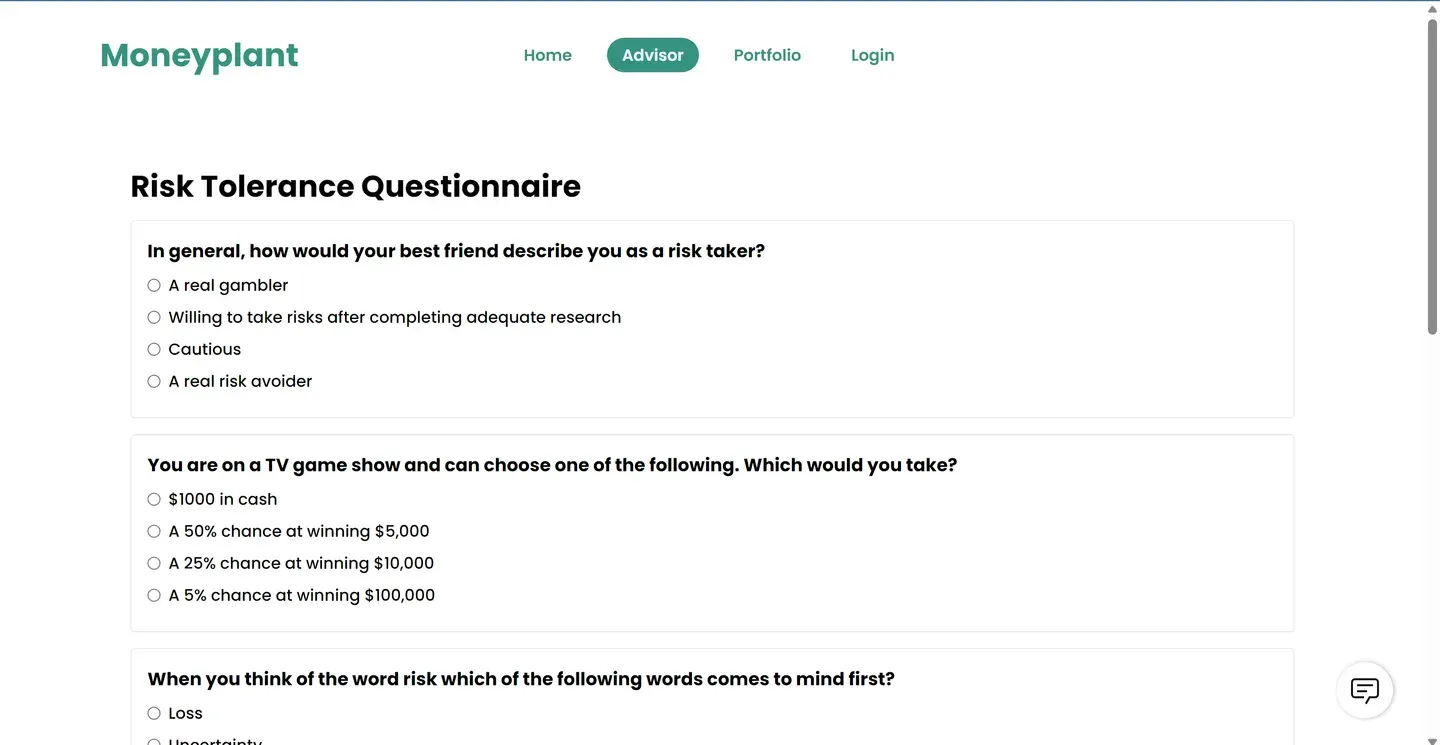
A risk-tolerance questionnaire sets the investor’s risk aversion. An LSTM trained on historical prices forecasts each of the 11 S&P sectors, and those forecasts become the views in a Black-Litterman model that starts from a near-equal prior and ten years of sector covariance. The output is a set of sector weights.
A React app with the questionnaire, a portfolio page with allocation charts and a TradingView chart, a watsonx Assistant chatbot, and breathing reminders to keep investing calm. A Django REST Framework backend with registration, JWT login and portfolio endpoints.
My part: the whole React frontend, the Django backend and auth, and the questionnaire. Sourish Pasula built the LSTM and Black-Litterman optimizer, and Noel Emmanuel the portfolio API model.
Results
- Third place in the PIMCO Challenge at TAMUhack X.
- Built in 24 hours. In the submitted code the Advisor page’s call to the portfolio API is commented out, so the optimizer ran as its own script rather than end to end from the questionnaire.